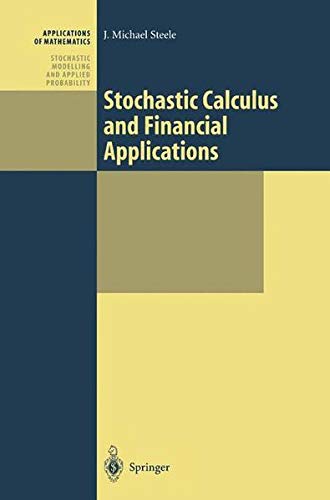
Stochastic calculus and financial applications / J. Michael Steele.
Material type: TextSeries: Applications of mathematics ; 45.Publication details: New York : Springer, ©2001.Description: ix, 300 P. : ill. ; 23 cmISBN:
- 9781468493054 (electronic bk.)
- 1468493051 (electronic bk.)
- 519.2 21
| Item type | Current library | Call number | Copy number | Status | Barcode | |
|---|---|---|---|---|---|---|
 Books |
Central Library, KUET On Display | 519.2 STE (Browse shelf(Opens below)) | 01 | Not For Loan | 3010063164 | |
|
Books
|
Central Library, KUET General Stacks | 519.2 STE (Browse shelf(Opens below)) | 02 | Available | 3010063165 |
Includes bibliographical references (pages 294-295) and index.
Random Walk and First Step Analysis -- First Martingale Steps -- Brownian Motion -- Martingale: The Next Steps -- Richness of Paths -- Itô Integration -- Localization and Itô's Integral -- Itô's Formula -- Stochastic Differential Equations -- Arbitrage and SDEs -- The Diffusion Equation -- Representation Theorem -- Girsanov Theory -- Arbitrage and Martingales -- The Feynman-Kac Connection -- Appendix I. Mathematical Tools -- Appendix II. Comments and Credits -- Bibliography -- Index.
Electronic reproduction. Ipswich, MA Available via World Wide Web.
There are no comments on this title.